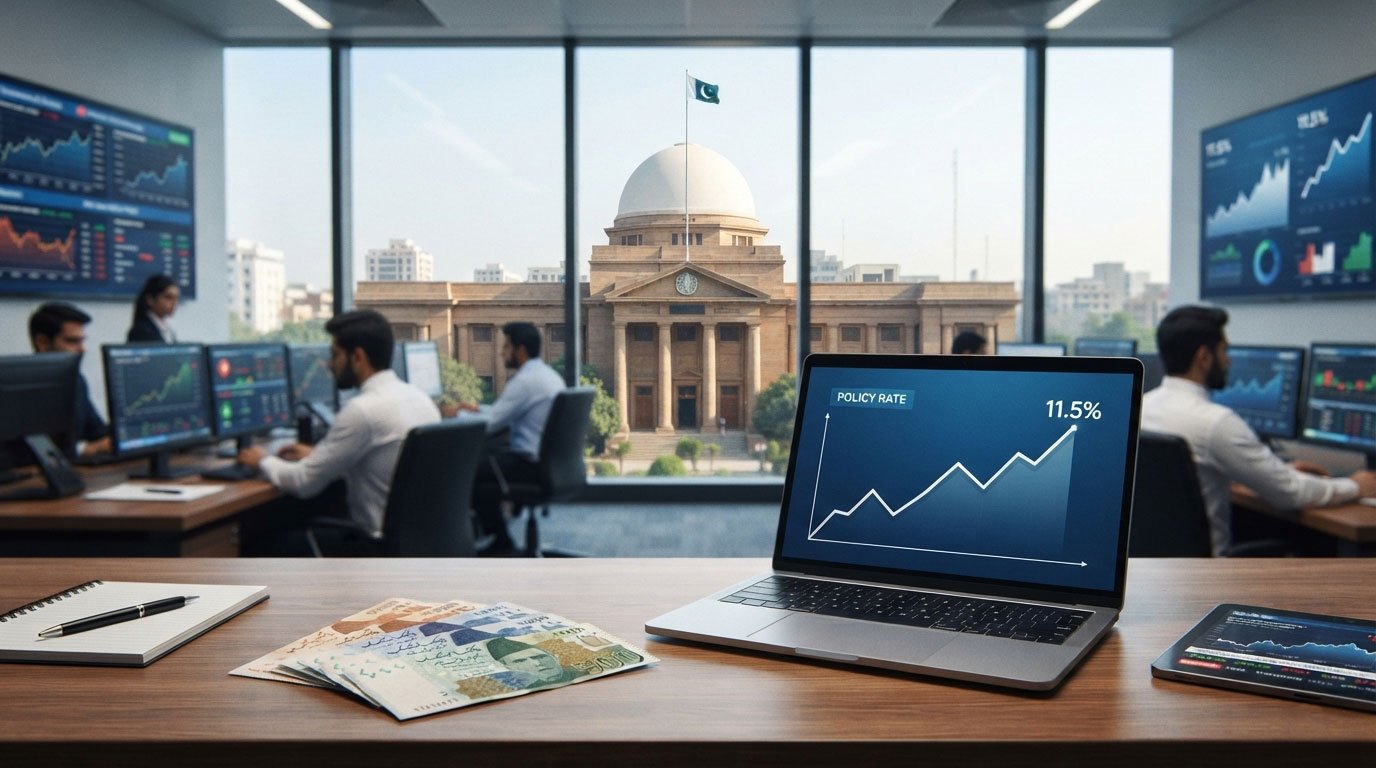
The State Bank of Pakistan (SBP) has decided to keep the policy rate unchanged at 11.5% following the Monetary Policy Committee (MPC) meeting held on September 14, 2026.
The latest decision means the benchmark policy rate remains at the same level rather than being increased or reduced. SBP’s official website confirms the 11.5% policy rate and the September 14 monetary policy decision. State Bank of Pakistan+1
The decision comes as Pakistan continues to deal with inflationary pressures, higher energy costs and uncertainty in the global economic environment. Arab News+1
What Is Pakistan’s Current Policy Rate?
As of September 16, 2026, the SBP policy rate is:
| Indicator | Current Rate |
|---|---|
| SBP Policy Rate | 11.50% |
| Overnight Reverse Repo Ceiling | 12.50% |
| Overnight Repo Floor | 10.50% |
These figures are listed by the State Bank of Pakistan in its current economic data. State Bank of Pakistan
The interest-rate corridor therefore remains 10.50% to 12.50% around the 11.50% policy rate.
Why Did SBP Keep the Policy Rate Unchanged?
The Monetary Policy Committee considered recent economic developments and the risks facing the economy before deciding to maintain the rate.
Recent reporting on the decision highlighted continued uncertainty surrounding energy prices and the wider international economic environment. Arab News+1
Keeping the rate unchanged allows the central bank to maintain its existing monetary-policy stance while continuing to monitor inflation and other economic indicators.
What Does the 11.5% Policy Rate Mean for Pakistan?
The SBP policy rate does not directly determine the interest rate of every bank loan or deposit. However, it has an important influence on borrowing costs throughout the financial system.
1. Bank Loans
When the policy rate remains high, borrowing can remain relatively expensive.
This can affect:
- Personal financing
- Business loans
- Working-capital financing
- Auto financing
- Housing finance
- Credit facilities
The actual rate charged by a bank depends on the type of financing and the bank’s pricing formula.
2. Home Financing
People planning to buy or build a house may continue to face relatively high financing costs where their financing is linked to market-based rates.
A policy-rate change can eventually influence floating or variable financing rates, although the exact impact depends on the terms of the individual loan.
3. Business Financing
Businesses also watch SBP policy decisions because financing costs can affect investment, expansion and working capital.
A higher interest-rate environment can increase the cost of borrowing, while lower rates can reduce financing costs when banks pass the change through to customers.
4. Savings and Deposits
The policy rate can also influence returns available on various bank deposits and other interest-bearing instruments.
However, deposit rates differ between products and banks, so customers should check the current rate offered by their own bank.
Has the SBP Policy Rate Changed in 2026?
The policy rate has moved during 2026.
The SBP increased the policy rate by 100 basis points to 11.50% effective April 28, 2026. State Bank of Pakistan+1
It subsequently maintained the rate at 11.50%, including the latest decision announced after the September 14 MPC meeting. State Bank of Pakistan
Current Position
Policy Rate: 11.50%
This is therefore the key benchmark rate businesses, banks and consumers are currently watching.
What About Inflation?
Inflation is one of the major factors monitored by central banks when setting monetary policy.
The latest policy decision comes at a time when Pakistan is also facing higher fuel and energy costs. Petrol and high-speed diesel prices were increased again for prices applicable from September 16, 2026, with petrol rising to Rs384.34 per litre and HSD to Rs415.83 per litre. Dawn
Higher energy costs can affect transportation, production and other parts of the economy.
What Does This Mean for Ordinary Pakistanis?
For consumers, the immediate message is that the SBP benchmark rate has not changed.
This means there is no new policy-rate reduction that would automatically make all bank financing cheaper.
At the same time, people with existing loans should not assume their monthly payment will change simply because the SBP made an announcement. The impact depends on the loan agreement and whether its pricing is fixed or linked to a benchmark.
What Should Borrowers Do Now?
People considering new financing should compare:
- Interest/profit rate
- Fixed vs variable pricing
- Processing charges
- Early settlement charges
- Insurance or takaful costs
- Total repayment amount
- Loan tenure
Rather than looking only at the advertised monthly installment, borrowers should calculate the total amount payable over the full financing period.
What Should Depositors Check?
People keeping money in bank deposits should compare the actual return offered by different products.
Important factors include:
- Annual profit/interest rate
- Deposit tenure
- Payment frequency
- Minimum balance
- Tax treatment
- Early withdrawal conditions
The SBP policy rate is an important market indicator, but it is not the exact deposit rate for every bank account.
What Happens Next?
The SBP’s monetary policy calendar shows the next scheduled MPC meeting after September is October 26, 2026, with the policy decision scheduled for the following day according to the published calendar. State Bank of Pakistan
Until then, economic indicators such as inflation, exchange rates, energy prices and external-sector developments will remain important factors for the monetary-policy outlook.
Frequently Asked Questions
What is the current SBP policy rate in Pakistan?
The current State Bank of Pakistan policy rate is 11.50% per annum as of September 2026. State Bank of Pakistan
When did SBP last announce its policy-rate decision?
The latest Monetary Policy Committee meeting was held on September 14, 2026, when the policy rate was kept unchanged at 11.5%. State Bank of Pakistan
Will bank loan rates immediately decrease?
No. Since the SBP did not cut the policy rate, there is no new policy-rate reduction. Individual loan rates also depend on each bank’s pricing structure and the terms of the financing agreement.
Does the SBP policy rate affect home loans?
It can influence financing costs, particularly for variable-rate or benchmark-linked financing, but the exact impact depends on the individual bank and financing agreement.
What is the next SBP policy meeting?
According to the SBP monetary-policy calendar, the next scheduled MPC meeting is October 26, 2026, with the decision scheduled for October 27. State Bank of Pakistan
Final Thoughts
The State Bank of Pakistan has kept the policy rate at 11.5% in its September 2026 decision. The unchanged rate means Pakistan’s monetary-policy stance remains at the current benchmark level while the central bank continues to monitor inflation, energy prices and wider economic conditions. State Bank of Pakistan+1
For consumers and businesses, the practical impact will depend on individual loan, financing and deposit arrangements rather than the policy rate alone.
Official Reference
State Bank of Pakistan: SBP Official Website
About the Author